

Self - Credit Builder
Self Financial, Inc.
- 4.5
- 37.67K Reviews
- 1.00M
- Downloads
- Free
- Price
Screenshots
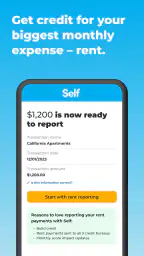
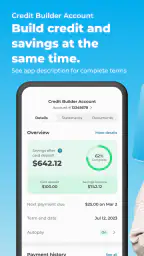
Self - Credit Builder Pros and Cons
Pros
- Easy to use interface.
- Boosts credit score effectively.
- Affordable monthly fees.
- No hard credit check required.
- Secure payment processing.
Cons
- Limited withdrawal options.
- Requires a bank account.
- No instant credit score update.
- Customer service could improve.
- Reports to only two credit bureaus.
 Analysis by All-app
I approach Self - Credit Builder as a practical credit-building tool, not a quick fix. Its central idea is to give people a structured way to work toward a payment history without starting with a conventional credit card. That can be appealing if you are new to credit or trying to make your finances feel more organized, but it still asks for steady payments and patience. I would begin by checking whether that commitment fits my actual monthly budget, rather than treating the app as a shortcut to a particular score.
Where people tend to get stuck
The biggest hurdle is often not tapping through the app; it is understanding what a credit-builder account can and cannot do. It is designed around a payment routine, so its value depends on keeping that routine manageable. Someone expecting an immediate score change, or hoping that installing a finance app alone will repair a credit profile, is likely to be disappointed. Credit histories take time to develop, and an app cannot make every lender assess a borrower in the same way.
There is also a difference between seeing progress inside an account and seeing the same progress reflected in a credit profile. Those are related, but they are not identical tasks. I would use the app’s dashboard to follow the account activity, then check credit information through a suitable reporting source separately. If the two do not appear to line up at first, I would avoid assuming that a single screen tells the whole story.
Setup checks that make the routine easier
Before opening an account, I would work out the amount I can reliably spare each month after essentials and irregular bills. A payment that looks small in a calm week can be awkward when a car repair or utility bill lands. Choosing a commitment that leaves breathing room is more useful than selecting the most ambitious option. The app is most helpful when its schedule fits normal life, not when it forces a budget to become fragile.
Self is a finance app from Self Financial, Inc., and its store summary describes credit-building or cash access without requiring a credit check. I would still read the terms for the specific account or option I intend to use before committing, especially to understand payment timing, total costs, and any conditions attached to cash access. “No credit check required” should not be read as “no eligibility rules” or “no responsibilities”; it is a reason to explore the option, not a substitute for reviewing the details.
Recovering when the workflow goes off track
If a payment reminder arrives at a bad time, I would open the app and confirm the account status and upcoming due date rather than relying on memory or an old notification. If a payment appears missing or a screen does not update, the useful first step is to compare the app’s account information with the relevant payment record and allow for ordinary processing time. I would not make a second payment just because an interface looks stale; I would check the transaction details first and contact the provider through its official support route if the status remains unclear.
For a sign-in problem, I would check the basics before repeatedly trying different passwords: confirm I am using the right sign-in details, make sure the app is current, and try again with a stable connection. If the issue persists, account support is a better next move than creating another account, which could make it harder to keep the records straight. These are simple checks, but they help separate a temporary display or access problem from an account question that needs a direct answer.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
When the app may not be the cause
A credit score can change for reasons beyond one app or account, and different credit decisions may use different information. If the score you see elsewhere does not move as expected, I would first review the underlying report for errors or other changes instead of assuming the app has failed. The account can support a longer-term routine, but it cannot correct inaccurate information elsewhere or control how another company evaluates an application.
This distinction matters when deciding what kind of help you need. If your main problem is a mistake on a report, focus on the relevant reporting agency’s dispute process. If you need money quickly, compare available borrowing choices and their costs rather than opening a credit-building account solely for immediate cash. If your priority is learning basic credit concepts, the app’s educational material can be a starting point, but it should not replace reading the terms of any financial product you use.
Getting Started with Self - Credit Builder
First things first, downloading and setting up the Self - Credit Builder app is a breeze. Available on both Android and iOS, the app welcomes you with a clean and user-friendly interface that even the most tech-averse among us can navigate without breaking a sweat. After a quick sign-up process, I was ready to embark on my credit-building journey.
How It Works
The concept behind this app is both simple and genius. Essentially, Self allows you to open a credit-builder account, which is like a savings account with a twist. Instead of depositing a lump sum, you make small monthly payments, which Self reports to all three major credit bureaus. This not only helps establish a payment history but also gradually builds your credit score over time.
Personally, I found this approach a breath of fresh air. Instead of the usual cycle of applying for credit cards with sky-high interest rates, Self offers a straightforward, low-risk alternative that empowers users to take control of their financial futures.
Features That Stand Out
One of the standout features of this app is its accessibility. You can choose a plan that suits your budget, with terms ranging from 12 to 24 months. This flexibility means you can build credit at your own pace without feeling overwhelmed.
Another feature that caught my attention is the educational resources. Self offers a wealth of information on credit scores, financial tips, and much more. For someone like me, who is always eager to learn, these resources are invaluable.
The User Experience
The user experience on the Self - Credit Builder app is, in a word, seamless. Notifications remind you of upcoming payments, ensuring you never miss a due date. Plus, the app's dashboard makes it easy to track your progress, so you always know where you stand on your credit-building journey.
I also appreciate the transparency of the app. There are no hidden fees, and everything is laid out in simple terms. For anyone who has ever been burned by unexpected charges, this transparency is a huge relief.
Final Thoughts
In conclusion, the Self - Credit Builder app is a fantastic tool for anyone looking to take charge of their credit journey. It combines simplicity with effectiveness, making it accessible to everyone, regardless of their financial literacy level. So, if you're ready to transform your credit score without the stress, give Self a try. Trust me, your future self will thank you!
Who benefits most, and who should look elsewhere
I see the clearest fit for someone who wants a defined monthly routine to begin establishing credit and can keep that payment affordable across ordinary and difficult months. It may also suit a person who has avoided credit cards because they do not want to manage revolving balances, though that does not make the account universally better. Someone who already has a strong payment history, needs to reduce expensive debt, or has urgent bills to cover may get more value from a different financial step.
Compared with a secured credit card, a credit-builder account shifts the task away from making purchases and managing a card balance. A secured card can be more useful for someone who wants to practice card use and can reliably pay the statement in full; Self’s account-based routine may feel simpler for someone who wants a scheduled payment instead. Neither approach guarantees a score outcome, and the right choice depends on the costs, terms, and habits a person can sustain. I would compare the full commitment, not just the headline feature.
A realistic month-to-month use case
Imagine someone paid twice a month who wants to build a more consistent financial routine. They could review the account and due date after payday, reserve the payment amount before discretionary spending, and use a calendar reminder as a backup to app notifications. If an unusually large bill arrives, checking the budget early gives them time to understand their options rather than waiting until a payment is already late. This workflow is more useful than checking the score every day, because it focuses attention on the behavior the account is meant to support.
A less obvious but worthwhile habit is to keep a small record of account actions, such as the date a payment was made and when its status changed. That makes it easier to ask a precise support question if a transaction is delayed or unclear. It also prevents a common mistake: confusing a notification, which is a prompt, with confirmation that a payment has completed. I would treat the dashboard as a monitoring aid, while keeping the bank or payment record available when reconciling an uncertain transaction.
Costs, expectations, and choosing an alternative
The app is free to install, but that does not mean every financial product or account inside it is free. I would look beyond the initial setup and calculate the total obligation across the plan, including any applicable fees or costs shown in its terms. That is especially important if cash access is part of the reason for considering it: compare the amount received with the amount and schedule you must repay or otherwise commit to, and do not assume the convenience makes it the cheapest option.
Self is a focused alternative to general budgeting apps, which can help organize spending but do not themselves create a credit-building account. It is also different from credit-monitoring tools, whose main job is to show reports or score information rather than establish a payment routine. If your goal is simply to see what is on your report, a monitoring or reporting service may be a better first stop. If your goal is to avoid missed bills, a calendar or budgeting tool may solve that problem with less financial commitment.
What I would check before committing
The app is listed as free, is rated for Everyone, and its Android release requires version 5.0 or later. Self Financial, Inc. released it on March 30, 2018; the current version is 6.23.0. It has a 4.5 average from around 91,000 ratings, with more than 1 million installs. Those figures suggest broad use, but they do not tell me whether a particular account is right for my budget. I would read the current in-app terms and confirm that the option I want is available where I live before making a decision.
It is also worth asking what success means before starting. If success means building a habit and adding a positive payment record over time, the structure may be appealing. If success means a guaranteed score increase by a certain date, I would choose another expectation: credit outcomes depend on the wider report and the scoring method, not only on one account. That distinction helps prevent frustration and keeps the decision grounded in what the app can reasonably support.
My practical verdict
Self is most compelling when I want a guided, account-based way to work on credit and can commit to its payments without straining my budget. The educational content and progress view can make an unfamiliar process easier to follow, while reminders give the routine a useful nudge. Its limitations are equally important: it is not a quick repair service, it cannot resolve report errors elsewhere, and the cost and account terms deserve careful attention before signup.
For a person starting from little or no credit history, or someone who prefers scheduled payments to managing a credit card, I would consider it after checking the full terms and monthly affordability. For anyone dealing with urgent cash needs, unstable income, or a report dispute, I would address those needs directly and compare other options first. Self is a sensible tool for a specific job, not a universal answer to every credit or money problem.
How I would describe the app to a friend
Self Financial’s finance app is free to download and has a 4.5 average from around 91,000 ratings, alongside roughly 38,000 written reviews. I would describe it as a structured way to approach credit building, not a promise that a score will rise on demand. The store summary highlights building credit or accessing cash without a credit check; in practice, I would still separate those goals and examine the terms for whichever option I planned to use.
My recommendation would be simple: install it only if you are ready to compare the account’s full commitment with your budget and keep up a steady routine. The Android app is rated for Everyone and supports Android 5.0 or later; it is also available on iOS. I like the idea of making credit building less intimidating, but the best result comes from realistic expectations, careful reading, and payments that remain manageable when life gets expensive.
Frequently Asked Questions
What is Self - Credit Builder and how does it work?
Self - Credit Builder is a financial app designed to help users build or improve their credit scores. It works by allowing users to take out a small loan, which is held in a Certificate of Deposit (CD) account. Users make monthly payments towards the loan, which are reported to credit bureaus. Once the loan is paid off, users can access the funds, helping to establish a positive credit history.
Are there any fees associated with using Self - Credit Builder?
Yes, there are fees associated with using Self - Credit Builder. Upon opening an account, users must pay a non-refundable administrative fee. Additionally, there are interest charges on the Credit Builder Account loan. It's important for users to review the terms and conditions, including all applicable fees, before committing to ensure it fits their financial plan.
Is Self - Credit Builder available for both Android and iOS devices?
Yes, Self - Credit Builder is available for both Android and iOS devices. Users can download the app from the Google Play Store for Android devices or the Apple App Store for iOS devices. This cross-platform availability ensures that a wide range of users can access the app's features, allowing them to build their credit scores conveniently.
How does Self - Credit Builder affect my credit score?
Self - Credit Builder can positively impact your credit score by reporting your monthly payments to major credit bureaus. Timely payments can help establish a good payment history, which is a crucial factor in credit scoring. However, missing payments can negatively affect your credit score, so it's important to make payments on time to reap the benefits.
Who is eligible to use Self - Credit Builder?
To be eligible for Self - Credit Builder, users must be at least 18 years old and a U.S. citizen or permanent resident. Additionally, users need a bank account, debit card, or prepaid card to make the monthly payments. It's designed for individuals looking to build or improve their credit history, especially those with limited or poor credit history.


